business
Pricing Strategies for Small Business: A Simple Guide That Protects Your Profit

Pricing your products is one of the hardest decisions a small business owner has to make. Price too high and customers walk away. Price too low and you work hard for almost nothing. The good news is that good pricing is not guesswork. It is a simple process: know your costs, understand your customers, and pick a strategy you can explain in one sentence.
This guide shows you pricing strategies for small business in a way that covers your costs, respects your customers, and leaves you a fair profit.
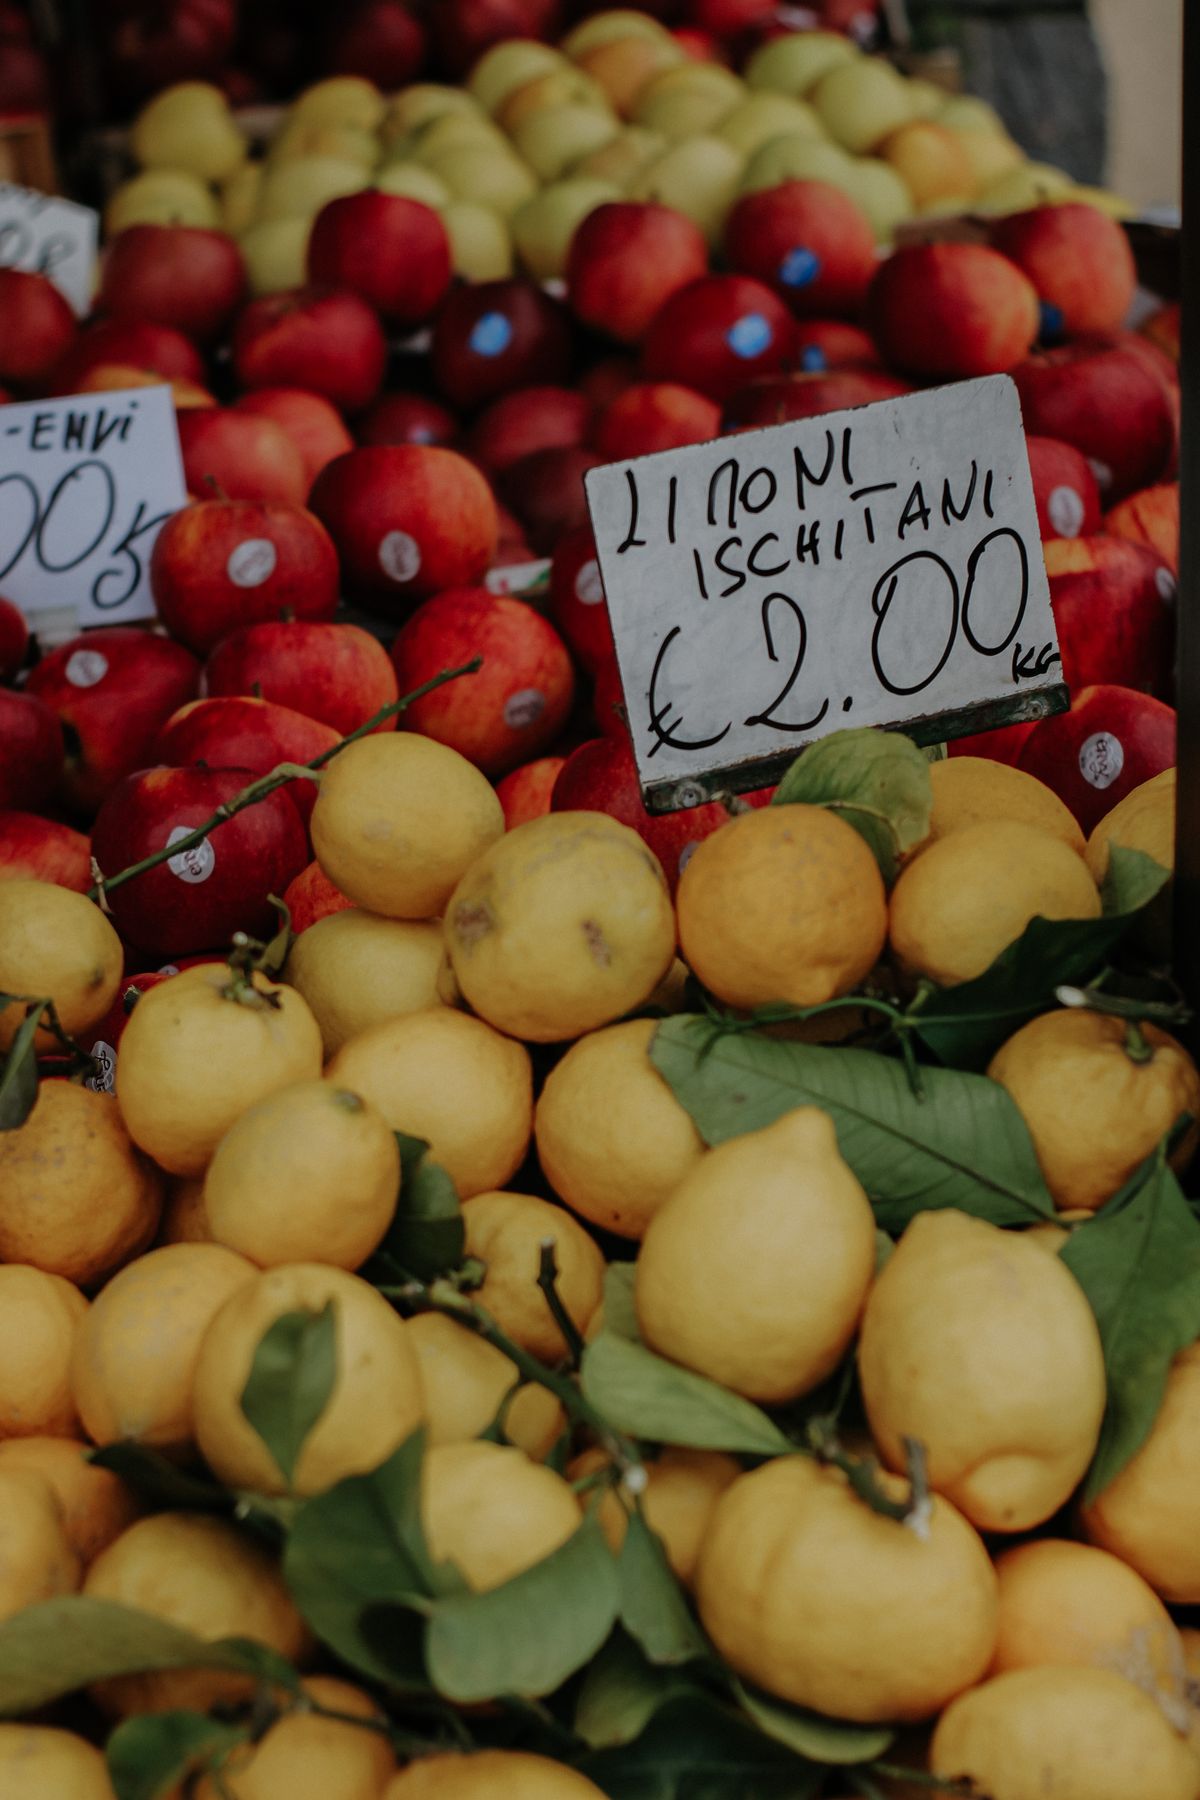
Why your prices matter more than you think
Your price does more than decide how much money comes in. It tells customers what your product is worth before they ever try it. A very low price can make people wonder about the quality. A very high price can make them look for a cheaper option. The right price sits in the middle: fair to the customer and fair to you.
Pricing also decides whether your business can survive. Many small businesses fail not because they have no customers, but because their prices never covered their real costs. Rent, materials, packaging, delivery, your own time — it all has to come from the price. If the maths does not work, no amount of sales will fix it.
Work out your true costs first
Before you set any price, list every cost that goes into one product. Start with the obvious ones: materials, ingredients, or the wholesale price you pay. Then add the hidden ones: packaging, labels, delivery, payment fees, and the share of your rent and bills that each sale has to carry.
Do not forget your own time. If a product takes you two hours to make and you pay yourself nothing, the business is quietly losing money. Decide on a fair hourly rate for yourself and add it to the cost. This is the step most new sellers skip, and it is the one that matters most.
Add everything up and you have your break-even cost — the lowest price at which you lose nothing. Your selling price must sit above this number, or every sale makes you poorer.
Pick a pricing strategy that fits your business
There is no single right way to price. These three pricing strategies for small business cover most situations, and you can mix them.
Cost-plus pricing is the simplest. Take your true cost and add a fixed percentage on top. If a candle costs you £4 to make and you add 50%, the price is £6. It is easy to calculate and it guarantees a margin on every sale. The weakness is that it ignores what customers are willing to pay.
These retail pricing strategies work whether you sell online, at a market stall, or from a small shop — the maths is the same, only the costs change slightly.
Value-based pricing starts from the customer instead. Ask what problem your product solves and what that is worth to the buyer. A handmade gift that saves someone hours of searching may be worth far more than its material cost. This approach often earns the best margins, but it needs honest research into what your customers value.
Competitor-based pricing looks at what similar businesses charge and positions you near them. It is useful when you are new and customers compare you directly with others. The danger is copying a competitor whose costs are different from yours. Use their prices as a guide, never as your only rule.
How to set prices for small business, step by step
Start with your break-even cost from the first step. Then check competitor prices for similar products and note the range customers already expect. Next, think about your position: are you the budget choice, the quality choice, or the convenient choice? Your price should match that position.
Now test a price inside the range that covers your costs and fits your position. Write it down with the maths behind it, so you can explain it to yourself later. Then launch, watch what happens, and adjust. Pricing is not a one-time decision. It is a habit you revisit as costs and customers change. A simple way to remember how to calculate selling price is this: true cost plus your margin equals your selling price.
A simple example helps. A jar of homemade jam costs £1.80 in fruit, sugar, jar, and label. Add £0.40 for delivery share and payment fees, and £1.00 for half an hour of your time. The true cost is £3.20. Similar jams sell for £4.50 to £5.50. Pricing yours at £4.95 covers costs, leaves £1.75 profit, and sits comfortably in the range customers expect.
Common pricing mistakes to avoid
The most common mistake is pricing by feeling instead of by numbers. “That sounds about right” is not a strategy. Always run the cost maths first, even for a small product.
Another mistake is copying the cheapest competitor. There will always be someone cheaper, usually because they cut corners you are not willing to cut. Competing on price alone is a race to the bottom that small businesses rarely win.
Discounting too often is a quiet killer. A sale every week trains customers to wait for the discount and never pay full price. Use discounts sparingly, for a clear reason, and for a limited time.
Finally, do not forget small costs that add up: card fees, packaging tape, the fuel for a market trip. Review your cost list every few months, because costs creep up silently and eat your margin.
When and how to raise your prices
Most small businesses wait too long to raise prices. If your costs have gone up, your order book is full, or you are turning work away, those are signs your price is too low. A small, regular increase is easier for customers to accept than one big jump after years of standing still.
Tell customers why, briefly and honestly. “Our prices have gone up slightly to cover rising material costs” is fair and understandable. Most customers accept a small rise when the quality stays the same. The few who leave were often the ones who cost you the most time anyway.
Raise prices for new customers first if you are nervous, then roll the change out to everyone. Keep a note of what changed and when, so you can see whether sales held steady.
Test your prices and keep reviewing them
Your first price is a starting point, not a final answer. Watch three things: how many people buy, how many ask about the price and walk away, and how much profit each sale leaves. If almost everyone buys without hesitating, your price may be too low. If many people love the product but never buy, it may be too high.
Try small changes. Raise one product by 5% and watch for a month. Change the price of a bundle instead of a single item. Ask a few loyal customers what they think the product is worth — you may be surprised how generous their answer is.
Review your prices at least twice a year, and every time a major cost changes. A price that was right last year may be wrong today, and a short review keeps your business healthy without drama.
Conclusion
Learning pricing strategies for small business comes down to three habits: know your true costs, choose a strategy that fits your customers, and review your prices regularly. You do not need to be the cheapest, and you do not need to apologise for charging fairly. A clear price that covers your costs and reflects your value is good for you and good for your customers. Start with one product today, run the numbers, and set a price you can stand behind.

How to Run a Successful Small Business: A Simple Guide That Works

How to Get More Customers for My Small Business: A Simple Guide That Works

Small Business Growth Strategies: A Simple Guide That Actually Works

Pricing Strategies for Small Business: A Simple Guide That Protects Your Profit

How to Make a Website for Small Business: A Simple Guide That Gets You Online

How to Register a Small Business: A Simple Guide That Gets You Started Properly

How to Manage Inventory for Small Business: A Simple Guide That Keeps Stock in Order

Small Business Customer Service Tips: A Simple Guide That Keeps Customers Coming Back
How to Accept Payments for Small Business: A Simple Guide That Gets You Paid Faster

How to Advertise Your Small Business Online: A Simple Guide That Brings Customers Without a Big Budget

How to Repurpose Blog Content for Social Media Without Starting From Scratch

How to Write a Professional Business Email That Gets a Reply

How to Set SMART Goals for a Small Business: A Practical Guide That Actually Works
How to Handle Customer Complaints in a Small Business: A Calm, Practical Guide That Turns Problems Into Loyalty
How to Create a Content Calendar for a Small Business
How to Track Small Business Expenses: A Simple System That Keeps Your Money in Order
How to Create a Small Business Content Marketing Plan That Actually Gets Results
How to Create a Content Calendar for Your Small Business: A Simple Monthly Plan That Keeps You Consistent
How to Set Up a Simple Referral Program for Your Small Business: A Beginner’s Guide That Brings in New Customers
How to Write a Mission Statement for Small Business That Guides Every Decision
How to Run a Successful Small Business: A Simple Guide That Works
How to Get More Customers for My Small Business: A Simple Guide That Works
Small Business Growth Strategies: A Simple Guide That Actually Works
Pricing Strategies for Small Business: A Simple Guide That Protects Your Profit
How to Make a Website for Small Business: A Simple Guide That Gets You Online
How to Register a Small Business: A Simple Guide That Gets You Started Properly
How to Manage Inventory for Small Business: A Simple Guide That Keeps Stock in Order
Small Business Customer Service Tips: A Simple Guide That Keeps Customers Coming Back
How to Accept Payments for Small Business: A Simple Guide That Gets You Paid Faster
How to Advertise Your Small Business Online: A Simple Guide That Brings Customers Without a Big Budget

 entertainment1 year ago
PYT Telegram: A Complete Guide to Understanding, Using, and Maximizing It

 entertainment1 year ago
OnionFlix: Everything You Need to Know About This Streaming Website
- education1 year ago
How to Become a Software Engineer: A Complete Guide
- others1 year ago
Nook vs Kindle: Which E-Reader Is Right for You?